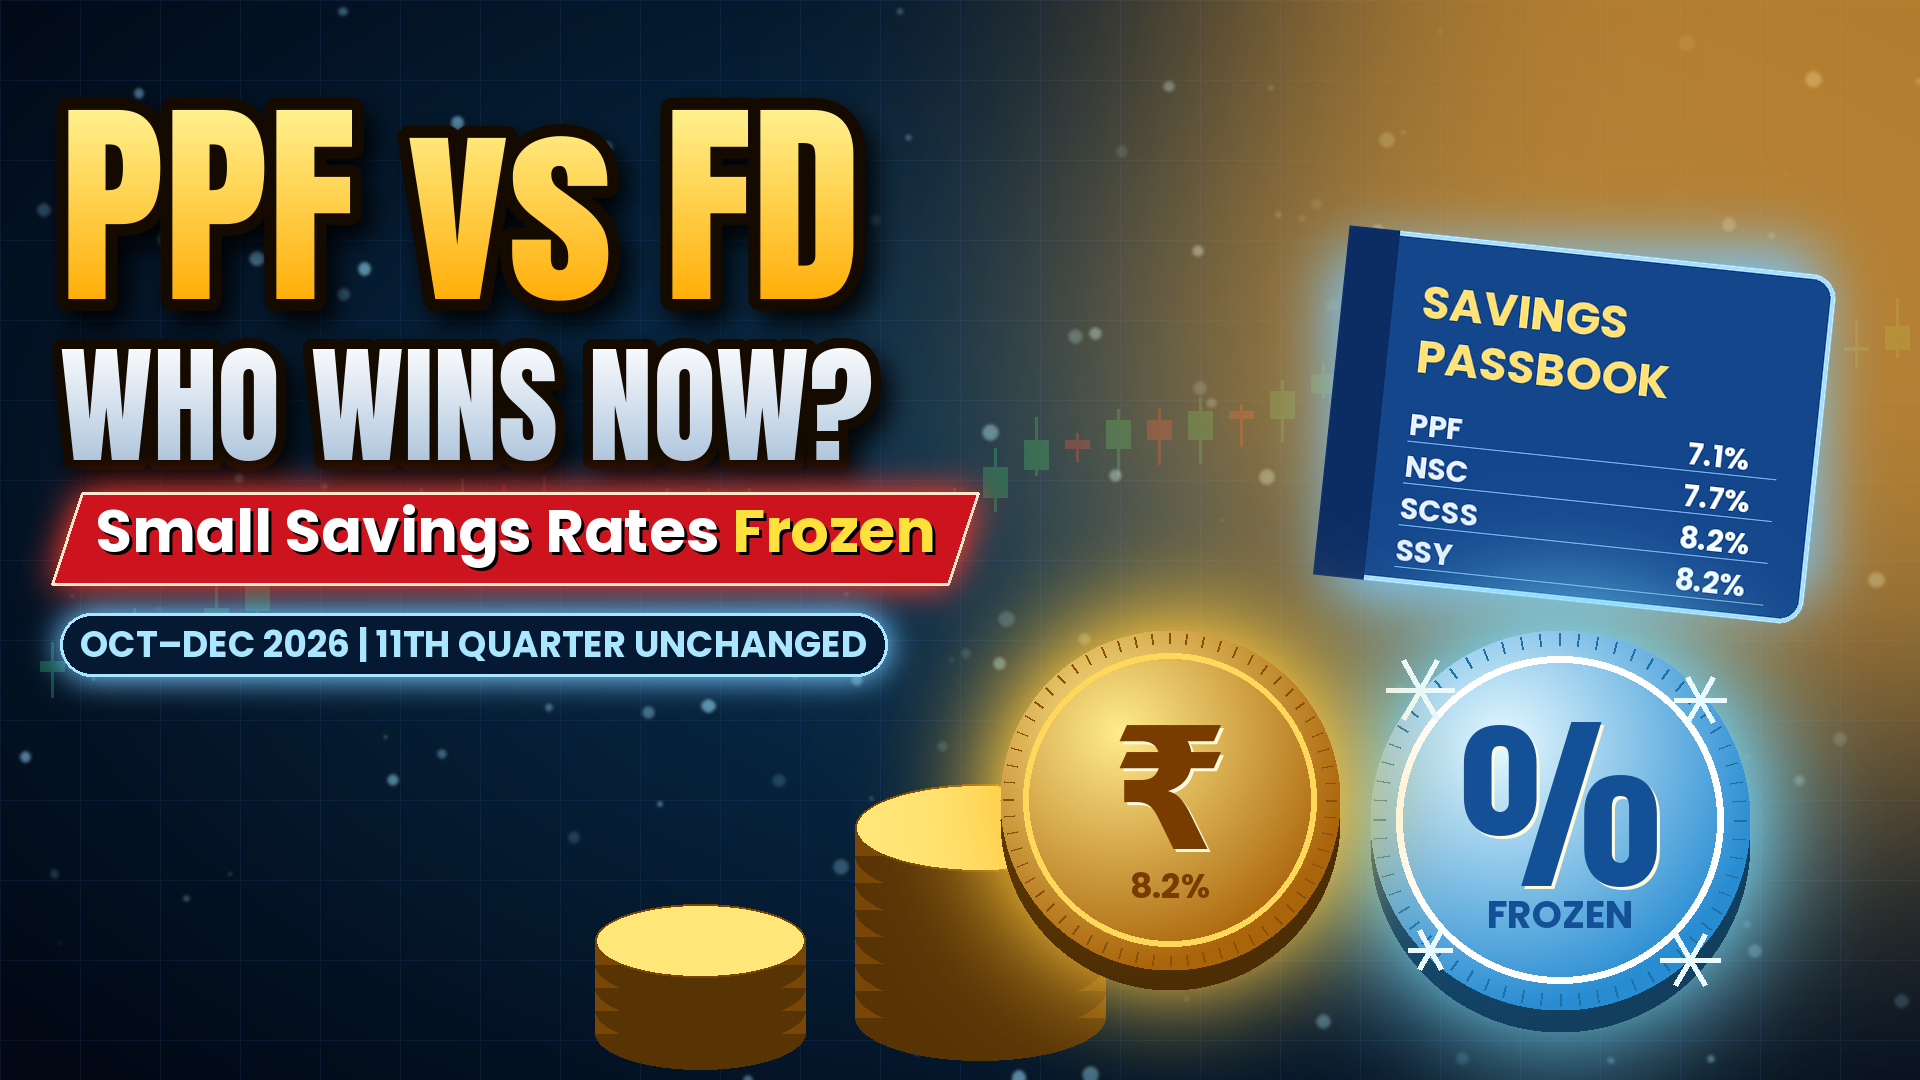
If you put money into the Post Office’s Senior Citizen Savings Scheme this quarter, you will earn 8.2 per cent a year. The best regular five-to-ten-year fixed deposit rate SBI lists for senior citizens is 7.05 per cent. That gap has lasted for months, because the government has now left small savings interest rates unchanged for the 11th straight quarter, with no revision since the January–March 2024 quarter. But the Reserve Bank of India announces its policy decision on October 7, and most economists polled by Bloomberg (34 of 40) expect a rate hike. So should you lock in PPF, NSC or SCSS rates now, or wait for bank FDs to catch up?
Here is what changed on October 1 (nothing), what is likely to change soon (possibly a lot), and how to think about where your safe money goes.
What the Government Announced
On September 30, 2026, the Ministry of Finance’s Department of Economic Affairs issued Office Memorandum F. No. 1/4/2019-NS. It states that rates on small savings schemes for October 1 to December 31, 2026 “shall remain unchanged” from the July–September quarter. The Department of Posts passed this on to every post office through SB Order No. 12/2026 on the same day. According to the PTI report carried by Business Standard, rates were last changed in the January–March 2024 quarter.
These are the rates that apply from October 1, 2026:
| Scheme | Rate (Oct–Dec 2026) |
|---|---|
| Post Office Savings Account | 4.0% |
| 1-Year Time Deposit | 6.9% |
| 2-Year Time Deposit | 7.0% |
| 3-Year Time Deposit | 7.1% |
| 5-Year Time Deposit | 7.5% |
| 5-Year Recurring Deposit | 6.7% |
| Senior Citizen Savings Scheme (SCSS) | 8.2% |
| Monthly Income Account (MIS) | 7.4% |
| National Savings Certificate (NSC) | 7.7% |
| Public Provident Fund (PPF) | 7.1% |
| Kisan Vikas Patra (KVP) | 7.5% (matures in 115 months) |
| Sukanya Samriddhi Account (SSY) | 8.2% |
Always confirm the rate at your post office or bank, or on India Post, before you invest.
Why “Unchanged” Is Bigger News Than It Sounds
Small savings rates are supposed to follow government bond yields. The framework recommended by the Shyamala Gopinath committee in 2011 links each scheme’s rate to the yield on government securities (G-secs) of a similar maturity, plus a spread. Since 2016, the government has reset these rates every quarter, using the previous three months of G-sec yields as the guide, as a Finance Ministry release explained at the time. In practice, the government has broad discretion, and it has used it.
Look at what bond yields are doing. The RBI’s homepage data for October 5, 2026 shows the benchmark 10-year G-sec (6.94% GS 2036) yielding 7.215 per cent. The 2029 bond yields 6.79 per cent and the 2031 bond 6.95 per cent. PPF, a 15-year product, pays 7.1 per cent. That is below what the government itself pays to borrow for ten years in the market.
So yields have gone up and small savings rates have not. For savers, that means two things:
- Today’s rates are not unusually generous compared with market yields, even if they look high next to bank FDs.
- The next review could go either way. If yields stay high, the formula supports an increase in the January–March 2027 quarter. The government also has fiscal reasons to keep its borrowing costs down. Nobody can promise a hike.
Small Savings vs Bank FDs, Side by Side
Here is how comparable tenors stack up, using rates published on bank websites as of early October 2026 (deposits below ₹3 crore):
| Tenor | Post Office | SBI (public) | HDFC Bank (public) |
|---|---|---|---|
| ~1 year | 6.9% (1-yr TD) | 6.25% (1 to <2 yrs) | 6.25% (1 yr to <15 months) |
| ~3 years | 7.1% (3-yr TD) | 6.30% (3 to <5 yrs) | 6.50% (3 yrs 1 day to <4 yrs 7 months) |
| 5 years | 7.5% (5-yr TD) | 6.05% (5–10 yrs) | 6.40% (4 yrs 7 months 1 day to 5 yrs) |
| Senior citizens, 5 years+ | 8.2% (SCSS) | 7.05% (5–10 yrs, incl. We-care premium) | 6.90% (4 yrs 7 months 1 day to 5 yrs); 6.65% above 5 yrs |
Sources: SBI retail term deposit rates (effective from December 15, 2025); HDFC Bank FD rates (applicable from August 19, 2026). Rates change often, so check on the day you invest.
At big banks, the post office wins at every tenor. Some small finance banks advertise higher rates: a BankBazaar compilation cited by The Economic Times lists up to 8.10 per cent for one-to-two-year deposits. Remember that bank deposits are insured by the DICGC only up to ₹5 lakh per depositor per bank, principal and interest combined. Small savings schemes are backed by the Government of India.
What ₹10 Lakh Actually Earns
Percentages can hide the rupee difference, so take a retired saver with ₹10 lakh to invest for five years.
- SCSS at 8.2 per cent pays interest every quarter: about ₹20,500 per quarter, or ₹82,000 a year.
- An SBI senior-citizen FD at 7.05 per cent (5–10 years) earns about ₹70,500 a year on simple annual terms.
That is roughly ₹11,500 more a year before tax from the government scheme, or about ₹57,500 over five years. Both are taxable at your slab, so the after-tax gap depends on your bracket.
For a cumulative option, the India Post rate chart cited by The Economic Times shows ₹10,000 in NSC growing to ₹14,490 at maturity in five years at 7.7 per cent, compounded annually. The arithmetic is simple, but in a high-inflation year it is worth doing before you renew any deposit on autopilot.
The RBI Factor: Why Timing Matters This Month
The RBI’s Monetary Policy Committee is meeting from October 5 to 7. The repo rate stands at 5.25 per cent. Retail inflation reached 4.82 per cent in August according to MoSPI, and many economists expect a 25-basis-point hike. That is an expectation, not a decision. The RBI may still hold.
If the RBI does hike, banks usually raise FD rates for new deposits and renewals over the following weeks. Your existing FD keeps the rate you booked. The post office works differently:
- Locked at purchase: Time deposits, NSC, KVP, MIS and SCSS keep the rate in force on the day you invest for their full term.
- Floating each quarter: PPF and SSY balances earn whatever rate is notified for each quarter, so future changes apply to money already in the account.
So locking in an 8.2 per cent SCSS rate today protects you if rates later fall. Waiting only helps if the government raises small savings rates in the January–March 2027 review, which is uncertain.
The Tax Picture Under the New Income-tax Act
From April 1, 2026, the Income-tax Act, 2025 replaced the 1961 Act. The familiar Section 80C deduction now sits in Section 123, with the eligible investments listed in Schedule XV. It still has an overall cap of ₹1.5 lakh a year and is available only under the old tax regime. PPF, SSY, NSC, SCSS and the 5-year post office time deposit remain eligible investments.
What happens to your interest decides your real return:
- Tax-free: PPF and SSY interest and maturity proceeds remain exempt.
- Taxable at your slab: Interest on SCSS, NSC, MIS, post office time deposits and bank FDs is added to your income.
A quick comparison for someone in the 30 per cent slab (ignoring surcharge and cess):
| Product | Headline rate | Approx. post-tax yield |
|---|---|---|
| PPF | 7.1% | 7.1% (tax-free) |
| 5-Year Post Office TD | 7.5% | ~5.25% |
| SBI 5–10 yr FD | 6.05% | ~4.24% |
| SCSS | 8.2% | ~5.74% |
For a high-slab taxpayer, PPF’s 7.1 per cent tax-free is worth about 10.1 per cent pre-tax. No bank FD comes close. For someone in the new regime with a low tax bill, the gap is much smaller, and the taxable schemes look better.
A Practical Framework (Not a Recommendation)
Different savers face different trade-offs. Use these as questions to ask yourself, not instructions:
- Retired and need regular income? SCSS pays quarterly at 8.2 per cent and is open to people aged 60 and above (and, subject to conditions, to retirees aged 55 to 60 and retired defence personnel aged 50 and above), up to ₹30 lakh per individual. That limit was raised from ₹15 lakh by a 2023 amendment. Compare it with senior-citizen FDs only after tax.
- Saving for a daughter’s future? SSY’s 8.2 per cent and tax-free status make it worth looking at if you are eligible. Lock-ins are long, so plan your liquidity separately.
- Long-term, tax-free compounding? PPF’s 15-year structure suits retirement-style goals. The rate floats, so treat 7.1 per cent as today’s rate, not a promise.
- Money you may need in one to three years? Consider splitting deposits across tenors (a “ladder”) so that part of your money comes up for renewal if FD rates rise after the RBI decision.
- Borrowing soon? A rate hike usually reaches floating-rate loans too. A strong credit score helps you get better terms. See our guides on what a credit score is and how to improve it and practical steps to raise your score fast.
Five Takeaways
- Small savings rates are frozen until December 31, 2026, the 11th straight quarter without a change (the last revision took effect in January 2024).
- The post office beats big-bank FDs at every comparable tenor right now, especially for seniors (SCSS 8.2% vs 7.05% at SBI).
- Rate locks differ. SCSS, NSC, KVP and time deposits fix your rate at purchase. PPF and SSY float every quarter.
- Tax decides the winner. In the 30 per cent slab, PPF’s tax-free 7.1 per cent is worth about 10.1 per cent pre-tax.
- An RBI hike helps new FDs, not old ones. Spread your timing instead of betting everything on one outcome.
What Happens Next
- October 7, 10 a.m. IST: The RBI MPC decision. Watch for bank FD revisions in the days that follow.
- October 12: MoSPI’s September CPI data, a key input for whether rates keep rising.
- Late December 2026: The government announces small savings interest rates for January–March 2027.
- Before March 31, 2027: If you use the old regime, plan your Section 123 investments early rather than in a March rush.
For more practical guides, browse our Personal Finance section or the Finance With Prahlad homepage.
Disclaimer: This article is for general information and education only. It is not investment, tax or financial advice. Interest rates, tax rules and scheme conditions change, so check the latest details with India Post, your bank or the Income Tax Department, and consult a qualified financial adviser or chartered accountant before you invest. Past or current rates do not guarantee future returns.